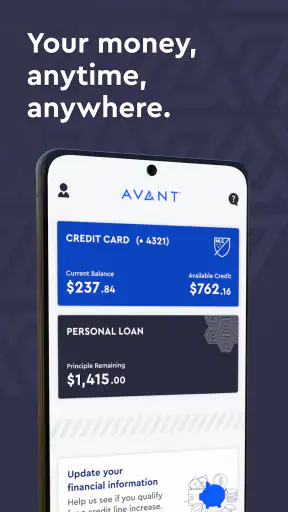
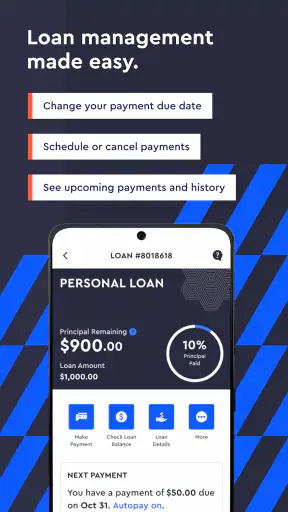
Managing a credit card or loan from a phone sounds simple, but the quality of a finance app is usually decided in small moments: checking whether a payment went through, finding a recent transaction, or confirming what needs attention before a busy day. I spent time with Avant as a mobile finance app from Avant, LLC, and found that its main appeal is focus. It is built around handling an Avant card or loan rather than trying to become a complete banking replacement.
That narrow purpose makes the app easier to understand than many financial tools that combine checking accounts, investing, budgeting, rewards, and bill management in one crowded screen. At the same time, it also defines the app’s limits. If you already use an Avant financial product, the app can put useful account actions in one place. If you are looking for a general-purpose money manager, it may feel too specialized.
How Avant feels during everyday account checks
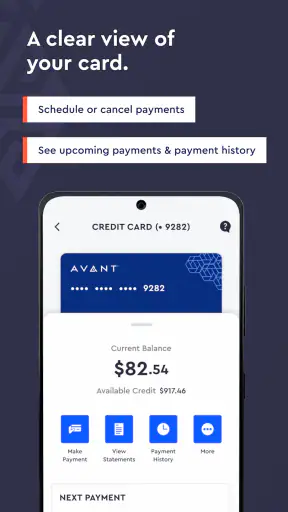
The first thing I noticed is that the app’s usefulness depends less on flashy extras and more on how quickly I can reach the information I need. The central tasks are practical: making a payment, reviewing transactions, and managing a card or loan. For a finance app, that is the right priority. I do not want to spend time exploring a complicated dashboard when I am checking an account before making a purchase.
My expectation for speed is therefore modest but important. Avant does not need to behave like a game or a social app. It needs to open without unnecessary friction, show account information clearly, and let me move from checking a balance to taking action without getting lost. In normal use, that focused design should feel more efficient than opening a full banking app filled with unrelated accounts and promotions.
The app is free to download, and its Everyone content rating makes it broadly approachable from an age-classification perspective. It requires Android 6.0 or later, which is useful for people who keep an older phone instead of upgrading frequently. The current version is 4.7.0, so compatibility still matters: an older operating system may meet the minimum requirement while offering a less comfortable experience than a newer device.
There is a useful distinction between app speed and financial processing speed. A screen can load quickly while a payment or account update may still depend on normal banking processing. I would not treat an immediate visual update as proof that a transaction has fully settled. After making a payment, I recommend checking the transaction area again later and keeping the confirmation details until the account reflects the change you expect.
A realistic payment-day routine
Imagine that I am preparing for a weekend trip and want to reduce the balance on my Avant card before leaving. I can open the app, review recent activity, choose the payment action, and verify the amount before submitting it. That is a more sensible workflow than relying on memory or searching through email notifications. The transaction list also gives me a second way to check whether a purchase I recognize has appeared.
The best habit here is to separate three checks: the amount I intend to pay, the account or product selected, and the confirmation after submission. Finance apps can make actions look deceptively quick, so slowing down for those checks is worthwhile. Avant is most helpful when I use it as a control panel for deliberate account maintenance, not as a place to make rushed decisions.
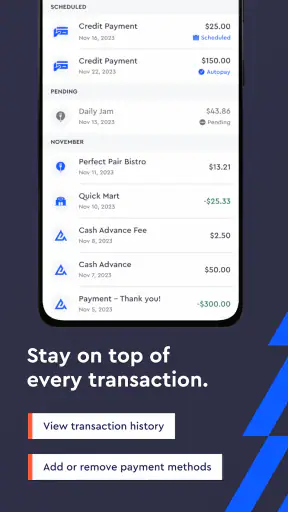
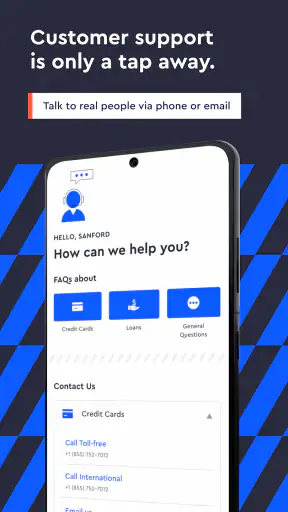
Another practical use is reviewing activity before contacting support about a suspicious or confusing charge. Looking through transactions first helps me identify the date, amount, and context of the entry. That does not replace formal dispute procedures, but it makes the next step clearer and reduces the chance of describing the wrong transaction.
What happens when the app is under heavier use
Heavy use in this case is not hundreds of files or demanding graphics. It is a cluster of financial tasks performed close together: opening the app, scanning several transactions, starting a payment, returning to the account view, and checking the result. The interface has a relatively narrow job, which should help it feel less overloaded than a broad personal-finance suite.
Still, a finance app can feel slow for reasons outside the interface itself. Account information may need to be retrieved, a payment action may require additional verification, and a transaction list may take time to reflect a new event. I would judge the experience by whether the app communicates each stage clearly, not simply by how fast the opening screen appears.
On a phone with limited storage or memory, I would keep expectations realistic. The app is not something I would install for entertainment and leave open all day; I would open it when needed, complete the task, and close it. That usage pattern is naturally light on resources. The more important concern is having enough free space for normal app updates and keeping the operating system in a supported condition.
One trade-off of a focused finance app is that it may feel lighter than a full banking application, but it also gives me fewer reasons to keep it open. That is a benefit for occasional account checks and a limitation if I want one app to show every financial relationship I have. Avant does not become a replacement for unrelated accounts simply because it displays card or loan information well.
Reliability matters more than visual polish
For me, reliability means being able to return to the same account information, understand what has happened, and recover sensibly when a task is interrupted. A payment app should not encourage guesswork after a weak connection, an accidental exit, or a delayed account update. The safest response is to reopen the app, inspect the transaction history, and confirm the current state before trying the action again.
This recovery habit is especially important with payments. If I tap a payment action and the screen does not immediately give me a clear result, I would avoid submitting the same payment repeatedly. I would first check whether the activity or payment history has changed. Repeating an action because the interface feels uncertain can create unnecessary confusion, even when the original attempt succeeded.
Avant’s strong user reception is encouraging: it holds a 4.7 average from around fifty-eight thousand ratings, with roughly five thousand four hundred written reviews. More than five hundred thousand installations also suggest that it is not an obscure experiment. Those figures do not guarantee that every device or account experience will be perfect, but they do make the app easier for me to consider than an untested finance tool.
I also appreciate that reliability is not just about avoiding crashes. Clear transaction presentation matters just as much. When I review activity, I want to recognize what I am seeing without having to reconstruct the account from scattered screens. A concise transaction view is valuable because it supports quick checks while still giving me a record to consult when something looks unfamiliar.
There is a limit to what any mobile app can control. Network interruptions, account servicing, maintenance, and delayed updates can all affect the experience. I would not use Avant as my only record for an important financial deadline. I would keep the relevant confirmation and, when timing is critical, allow enough time for the account to reflect the action instead of waiting until the last possible moment.
Older phones and everyday device constraints
The Android requirement of version 6.0 or later gives Avant a relatively accessible starting point for Android users with older hardware. That does not mean every older phone will feel equally comfortable. A device may technically run the app while having a dim screen, limited memory, slow storage, or an outdated browser component that affects modern account interfaces.
For a finance app, I would prioritize stability and visibility over decorative design. A user with an older phone should keep the device updated as far as its manufacturer allows, maintain free storage, and avoid running many heavy apps at the same time. Those steps are not special Avant features; they are sensible ways to reduce avoidable friction when handling financial information.
Resource demands are likely to be easier to manage when I use the app for short sessions. Checking a balance, reviewing transactions, or arranging a payment does not require continuous background activity from my perspective. I would not expect the app to serve as a budgeting tracker that constantly monitors every purchase across all accounts, so its role is naturally more contained.
That containment also helps with privacy habits. I would avoid using a shared phone for account access unless I can properly protect the device, and I would carefully review every screen before confirming a payment. The app’s Everyone rating describes content suitability, not a promise that financial decisions are suitable for every person. The responsibility for borrowing, repayment, and account security still rests with the user.
Where it beats broader finance alternatives
Compared with a general banking app, Avant has one clear advantage: concentration. If my main task is managing an Avant card or loan, I do not need to navigate checking accounts, savings tools, investment charts, or unrelated bank products. A dedicated account app can make a small number of important actions easier to find.
Compared with a budgeting app, the difference is even clearer. Budgeting tools are useful for categories, spending plans, and a wider view of household finances. Avant is more appropriate when I need to interact with the Avant account itself. I would use a budgeting app alongside it if I wanted a complete picture of rent, utilities, cash accounts, and other cards.
Compared with relying on a mobile website, a dedicated app can feel more convenient for repeated checks because the account experience is kept in one installed place. The trade-off is that an app occupies device storage and may require updates. Someone who checks the account only once every few months may prefer a browser, while someone who reviews activity weekly will likely benefit more from direct access.
The app is also not the right choice for someone who has no Avant card or loan to manage. Its value comes from connecting the mobile experience to that relationship. Installing it simply to browse general financial education or compare unrelated products would miss the reason the app exists.
Three habits that make the app more useful
My first tip is to use the transaction view as a routine checkpoint, not only as an emergency tool. A quick review after a few purchases can help me notice an unfamiliar entry while the details are still fresh. It also gives me a better sense of whether a payment or purchase is appearing as expected.
Second, I would make payment verification a two-stage process. Before submitting, I check the amount and the selected account action. After submitting, I return to the account activity and look for the resulting record. This small pause is more valuable than chasing the fastest possible tap sequence, especially when the connection is unreliable.
Third, I would avoid making a major payment decision based on a single glance at the opening screen. I would inspect the relevant transactions and confirm that the account information is current enough for the decision I am making. The app can make account management easier, but it cannot replace judgment about affordability, timing, or the broader cost of borrowing.
A fourth useful habit is to treat interrupted sessions carefully. If the app closes or the phone loses connectivity during an action, I would not immediately repeat it. I would reopen Avant, review the account activity, and use the available confirmation information before trying anything again. That approach reduces the risk of duplicate actions caused by uncertainty.
Who will appreciate it, and who should skip it
I would recommend Avant to an existing cardholder or loan customer who wants a straightforward mobile route to payments and transaction reviews. It is particularly suitable for people who prefer a focused tool over a large financial dashboard. The free price also removes a separate download cost, making it easy to try when the account relationship already exists.
I would be more cautious about recommending it to someone seeking a complete household finance system. If you need detailed budgeting, investment management, multiple-bank aggregation, or broad bill organization, a dedicated personal-finance platform will probably serve you better. Avant can remain one part of that setup, but it should not be expected to cover every financial task.
I would also skip it as a primary solution if my phone is unsupported, unreliable, or shared with other people. Financial access deserves a device I can protect and use consistently. An app can simplify account management, but it cannot compensate for a phone that frequently loses connectivity or cannot receive normal updates.
My performance verdict after regular use
Avant succeeds because it keeps its purpose recognizable. The experience is centered on managing an Avant card or loan, reviewing transactions, and making payments rather than surrounding those actions with a full collection of unrelated money tools. That focus should help it feel responsive during ordinary short sessions, while the limited scope keeps resource expectations reasonable on compatible devices.
Its most important weakness is also its narrow scope. I would not choose it instead of a full banking or budgeting app unless my financial needs are specifically tied to Avant. I would also remember that account updates and payment results may not be instantaneous, so careful verification is more important than assuming a quick screen change means everything is complete.
With over half a million installations and a 4.7 average, the app has earned a substantial audience, and the current 4.7.0 release gives Android users a clear version to maintain. My final view is positive but practical: Avant is best used as a focused account-management tool, not as an all-purpose financial command center. If that matches what you need, it can make routine checks and payment workflows more manageable. If your goal is broader money planning, pair it with a tool designed for that wider job rather than asking this app to become something it is not.
In everyday terms, I would keep it installed when I actively use an Avant card or loan, especially if I like checking transactions from my phone instead of relying on occasional website visits. I would use it deliberately, confirm important actions, and keep a wider budgeting method for the rest of my finances. That balance gives the app a sensible place in my routine without overstating what it can do.


